Where our experience with storm damage on Long Island helps
Storm damage on Long Island usually comes with an insurance file, a half-finished repair, and at least one open permit. Each of those frightens off an ordinary buyer and none of them frighten us.
We take open permits and violations on and resolve them after closing. We can work around an unresolved storm damage claim, and the contract will say plainly who receives the proceeds. If you are mid-claim and unsure whether to settle before selling, we will talk it through with you rather than rush you into the answer that suits us.
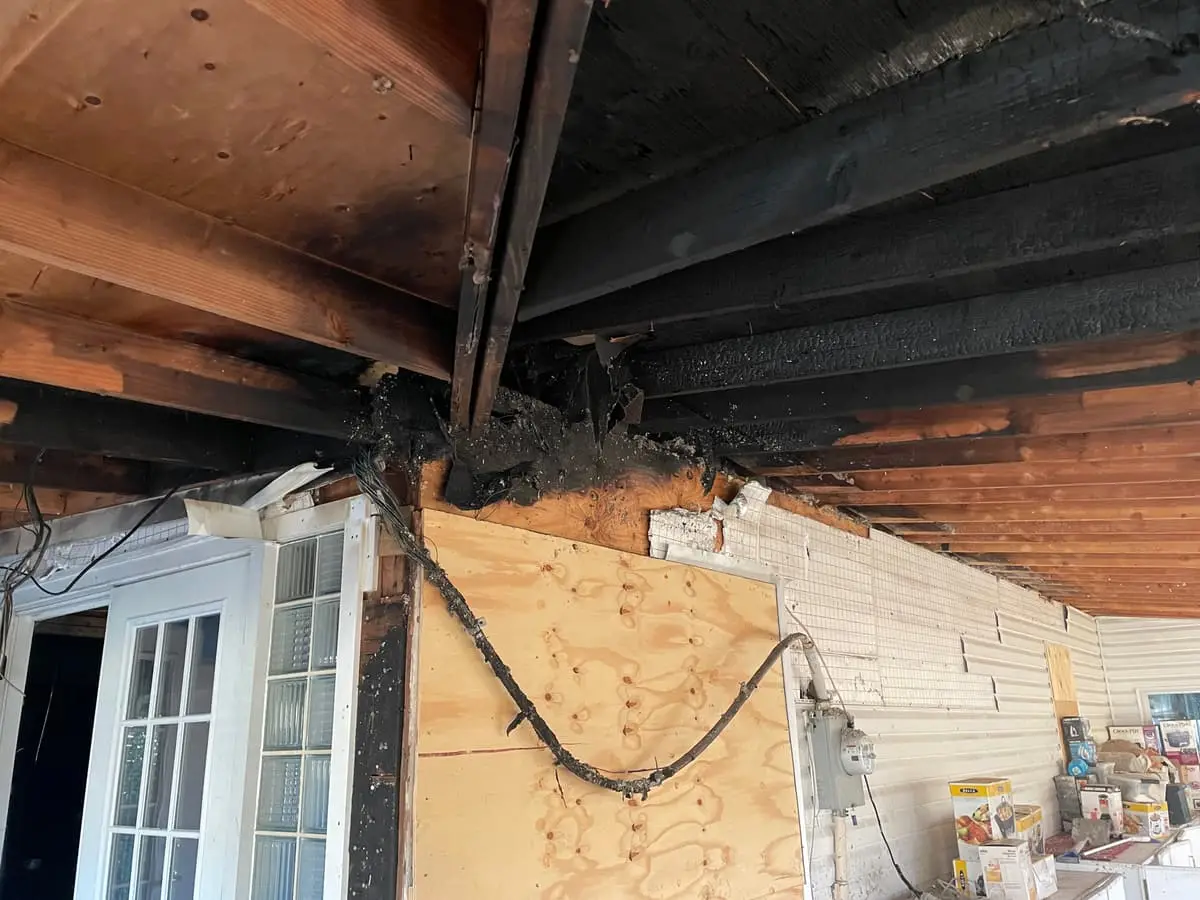
The Westbury house that was opened up and never closed
A house that was opened up and never closed is harder to sell than one that was simply damaged, because a buyer cannot tell what was done properly and what was abandoned.
Open permits make it worse. We take those on, permit side included, rather than asking you to resolve storm damage paperwork before closing. Half a roof, a gutted bathroom and a stalled permit are an ordinary purchase for us.
Why local knowledge changes the number
A four-bedroom on Sunnyside Lane. A three-bedroom on Montauk Court. A house on Lewis Avenue. All of them in Westbury, all bought by us.
Westbury is roughly 15,864 people in Nassau County, ZIP 11590, and the housing stock is mostly cape cod, colonial, ranch. Around Post Avenue and Jericho Turnpike, most of it is old enough that the mechanicals are on their second or third life. The Westbury stop pulls buyers who commute, which supports the good houses and does very little for the ones that need a roof. We know which of these streets take water, where the older systems fail first, and what the Westbury Union Free School District does to a resale price.
Flood zones and what they do to a Westbury sale
Two things stack against a storm-damaged house near the water: the repair itself, and what the flood zone does to anybody who needs a mortgage.
That combination is why these houses sit. It is also why a cash buyer who already understands the storm damage and the zone is usually the practical route. Nobody can guarantee a number before seeing a property, but neither of those facts alone stops us.
Tree and roof damage after a storm
Once the roof is open, a house stops being a house to a mortgage underwriter. That is the mechanical reason storm-damaged properties get quoted so far below what owners expect on the open market.
We are not underwriting anything, so the roof is a cost line to us rather than a disqualification. Tell us what the adjuster said, what got tarped, and what is still open, and we will price the storm damage honestly.
What you do not pay when you sell a storm-damaged house
Every line below is a cost of listing a storm-damaged house the retail way that simply does not arise here.
- Agent commission
- $40,050 at 5% of the Westbury median none
- Seller closing costs
- About $16,020 on a $801,000 sale. We can cover these. none
- Repairs to make it listable
- Everything a buyer would flag, paid for before you list none
- Cleanout and removal
- Charged by the truckload, and done before the first showing none
- Carrying costs while it waits
- Taxes, insurance and utilities while you spend 86 to 101 days finding a buyer and waiting for their loan none
The insurance claim: settle first, or sell first?
An open storm damage claim does not stop a sale. What it does require is a clear written agreement about who receives the proceeds, and that belongs in the contract rather than in a conversation.
Sometimes the cleanest outcome is that you keep the claim money and we buy the house for less. Sometimes the reverse nets you more. We will lay both versions out in numbers and let you and your attorney choose.
What the two paths cost in Westbury
These are the two routes open to you with a storm-damaged house, priced against what Westbury houses actually sell for.
Work it against Westbury's own numbers. The median sale here is $801,000. A 5% commission on that is $40,050, and seller closing costs of about 2% add roughly $16,020. Those are costs we can cover on our side. That is $56,070 gone before anyone counts the repairs it took to get the house listable.
There are two waits in a listed sale and people usually only count the first. In Westbury the median house takes about 41 days to go from listed to a signed contract. Then it waits again, typically 45 to 60 days, while the buyer's lender orders an appraisal and underwrites the loan. Call it 86 to 101 days from sign to keys, assuming nothing goes wrong.
The part worth understanding is what a signed contract actually guarantees, which is less than most sellers assume. A retail buyer with a mortgage contingency can walk away right up to the end. If they do not qualify, if the appraisal comes in under the price, if they change their mind and let the financing lapse. A share of deals die exactly there, after months of waiting, and the house goes back on the market with time on it. We are not borrowing anything, so there is no lender to satisfy, no appraisal to come in low and no contingency to exercise.
| Listing with an agent | Selling to us | |
|---|---|---|
| Sale price | $801,000 (Westbury median) | Our written offer |
| Commission | −$40,050 | None |
| Seller closing costs | −$16,020 | We can cover them |
| Repairs before listing | Out of pocket | None |
| Cleanout | Yours | Ours |
| Showings | Until it sells | One visit |
| Listed to signed contract | 41 days (Westbury median, once listable) | 24 hours to a written offer |
| Contract to closing | 45 to 60 days (waiting on the buyer's lender) | A date you choose |
| Total wait | 86 to 101 days if nothing falls through | Yours to set |
| Can the buyer walk? | Yes (mortgage contingency runs to the end) | No financing to fall through |
| Before repairs and carrying | $744,930 | The number we put in writing |
The listing column assumes a 5% commission and seller closing costs of about 2%. Both vary. We have not subtracted repairs or the cost of carrying the house while it sits, because those depend on the property. A house in good condition listed with a good agent can absolutely beat a cash offer, and we will say so if that is your situation.
Listing versus selling a damaged house as-is
The reason storm damage costs so much at the negotiating table is uncertainty. A retail buyer cannot price what is behind the wall, so they assume the worst and bid accordingly, then reduce again after the inspection.
We price the storm damage once, in writing, and we stand behind the number. That is generally worth more to a seller than a higher figure that shrinks twice before closing.
Common questions
There is an open storm damage claim. Can we still sell?
Usually yes, though who receives the claim proceeds has to be agreed and written into the contract. Your attorney will want to see it.
Do you need an engineer report?
No. We have engineers we use across Nassau County when a structural question comes up, and that is our cost rather than yours.
The storm repairs on our Westbury house have an open permit. Is that a dealbreaker?
Not at all. Permits attach to the property, so they come along with it. We handle the Westbury building department side ourselves once we own it.
The damage is from a storm years ago and was never finished. Do you still want it?
Yes. Old unfinished storm damage is one of the most common situations we buy, and the age of it does not count against you.
Can you close before the next storm season if we need to be out?
Usually. We set the closing date around you, and with storm damage already present there is rarely a reason to wait.